Your Weekly Update for Monday, September 21, 2026.
Beacon Rock Wealth Advisors is a dba of BR Capital, Inc. It is a financial planning and registered investment advisory firm in Camas, Washington. We are always available to answer your questions. Give us a call at (360) 735-1900 or send an email.
If you or someone you know is worried about retirement, send us an email or give us a call for a no-obligation Retirement and Social Security Analysis.
If this information is helpful to you, please forward this to a friend and ask them to subscribe at https://newsletters.beaconrwa.com/subscribe.
Have a great week!
Bill Roller
NMLS #107972
CHARTERED FINANCIAL ANALYST
CERTIFIED FINANCIAL PLANNERTM
CHARTERED MARKET TECHNICIAN
bill.roller@beaconrwa.com
Summary
Markets were MIXED last week. The Dow Jones Industrial Average was DOWN 1.69% to 51,682.64 while the S&P500 ended DOWN .08% to 7,650.50. The Nasdaq Composite ROSE 0.72% to 26,522.55. The annual yield on the 30-year Treasury FELL 2.3 basis point(s) to 5.331%.
Last Week
Closing Market Summary: Chip rally lifts stocks off session lows
The major averages staged an afternoon recovery on Friday, leaving the S&P 500 (+0.2%) and Nasdaq Composite (+0.4%) with modest gains while the DJIA (-0.2%) finished slightly lower. The improvement followed a weaker first half of the session, when rising Treasury yields and broad selling pressure had pushed the major averages to their session lows.
The recovery was driven largely by renewed strength in technology stocks and select mega-cap names rather than a broad-based advance. Only three S&P 500 sectors finished higher, while the Russell 2000 (-0.5%) and S&P Mid Cap 400 (-0.3%) continued to trail the large-cap indices. That divergence left the Nasdaq Composite as the only major index to finish the week with a week-to-date gain.
Semiconductor stocks provided the clearest source of leadership during the afternoon. The PHLX Semiconductor Index surged 2.8%, helping the information technology sector (+0.8%) finish atop the sector standings. Memory and storage names were particularly strong, with Sandisk (SNDK 1791.82, +177.43, +10.99%), and Seagate Tech (STX 858.79, +55.66, +6.93%) posting sizable gains amid continued enthusiasm surrounding AI data-center demand and tight storage supply.
Coherent (COHR 317.36, +21.38, +7.22%) was another standout, finishing among the best-performing S&P 500 components after announcing an expansion of its Pluggable Optical Line System portfolio targeting high-capacity interconnect requirements for cloud and AI infrastructure.
Mega-cap strength provided another source of support, leaving the Vanguard Mega Cap Growth ETF up 0.4%.
Amazon (AMZN 253.71, +2.52, +1.00%) was a standout and helped the consumer discretionary sector finish unchanged despite broader weakness within the group. The industrials sector (+0.5%) was another of the three sectors to finish higher, while the financials sector (+0.1%) received some support from continued strength in Coinbase Global (COIN 194.25, +20.28, +11.66%) and Robinhood Markets (HOOD 119.82, +10.01, +9.12%) following yesterday’s announcement of the SEC’s “Innovation Exemption” allowing crypto exchanges to offer tokenized equities and a surge in Bitcoin past the $81,000 mark.
The afternoon improvement came despite renewed pressure from Treasury yields. The 10-year note yield rose five basis points to 5.00%, leaving it two basis points higher for the week and reversing most of Thursday’s decline. Rate-sensitive areas consequently remained under pressure, with the utilities sector (-1.3%) finishing at the bottom of the standings and the iShares U.S. Home Construction ETF falling 1.3%.
The materials sector (-1.1%) was another pronounced laggard as Nucor (NUE 248.38, -16.76, -6.32%) and Steel Dynamics (STLD 235.26, -10.09, -4.11%) remained under pressure following disappointing third-quarter earnings guidance.
The communication services sector (-0.7%) also finished lower after beginning the session on a stronger note, with Netflix (NFLX 71.77, -3.54, -4.70%) weighed down by a Wells Fargo downgrade to Underweight from Equal Weight.
Crude oil moved in the opposite direction of Treasury yields, with WTI settling 1.8% lower at $100.24 per barrel, nearly flat for the week.
Friday’s session ultimately featured a meaningful recovery from broad morning weakness, but participation remained relatively narrow. Semiconductor and mega-cap strength was enough to lift the S&P 500 and Nasdaq into positive territory despite higher Treasury yields, weakness in small and mid-cap stocks, and losses across most S&P 500 sectors. The Nasdaq’s relative strength was also sufficient to leave it as the only major index with a gain for the week.
U.S. Treasuries had a poor finish to the week, which locked in weekly losses for the 10-year note and shorter tenors while the long bond continued its recent show of outperformance, recording a modest gain for the week. The 2-year note yield settled up five basis points to 4.74% (+10 basis points this week), and the 10-year note yield settled up five basis points to 5.00% (+2 basis points this week).
- Russell 2000: +15.3% YTD
- Nasdaq Composite: +14.1% YTD
- S&P 500: +11.8% YTD
- S&P Mid Cap 400: +10.5% YTD
- DJIA: +7.5% YTD
Reviewing today’s data:
- Industrial production was unchanged month-over-month in August (Briefing.com consensus: 0.3%) following an unrevised 0.2% increase in July. The capacity utilization rate was 76.3% (Briefing.com consensus: 76.4%) and unchanged from July. Total industrial production was up 1.4% year-over-year. The capacity utilization rate was 3.1 percentage points below its long-run average. The key takeaway from the report is that the softness stemmed from a decline in manufacturing output, yet that downturn could have been a simple case of attrition following increases in manufacturing output for seven consecutive months.
- Aug Leading Economic Index -0.1% (Briefing.com consensus 0.2%; Prior 0.2%)
This Week
S&P futures vs fair value: +53.00. Nasdaq futures vs fair value: +321.00.
Equity futures point to a firmly higher opening this morning as oil prices and Treasury yields retreat to start the week, with crude oil down roughly 2.5% to under $98 per barrel and the 10-year note yield down to 4.95%.
The market has been largely driven by oil and yields, as well as the performance of AI-related stocks in recent sessions, driving some choppy action last week that saw the Nasdaq Composite rise by 0.7%, while the DJIA slid 1.7%, its worst week since March.
Those themes remain in focus following last week’s FOMC rate hike, with the simultaneous pullback in oil and Treasury yields providing a favorable backdrop for equities this morning. On the geopolitical front, President Trump threatened another attack on Iran but said he remains open to meeting Iranian President Masoud Pezeshkian during this week’s United Nations General Assembly, according to CNBC. The potential for diplomacy comes as U.S.-Iran tensions remain an important influence on oil markets.
Strength is also extending to cryptocurrencies, with Bitcoin crossing the $85,000 mark to reach its best level since January.
The economic data calendar is relatively light this week following last week’s Fed decision, although President Trump and Chinese President Xi Jinping are scheduled to meet later this week, putting U.S.-China trade relations in focus. There is no economic data of note today.
In corporate news:
- OpenAI anticipates a cash burn rate of nearly $280 billion by the end of 2030, according to Financial Times.
- Anthropic’s IPO is likely to happen in November, as opposed to October, according to The Wall Street Journal.
- Novo Nordisk (NVO 21, -$2.03, -4.7%) said CagriSema achieved 12.4% weight loss versus 9.1% for tirzepatide at week 60 in a Phase III diabetes trial, meeting the superiority endpoint.
- Paramount Skydance (PSKY 88, +0.67, +6.6%) is in settlement talks with states as it aims to secure approval for its acquisition of Warner Bros. Discovery (WBD 2981, +2.01, +7.2%), according to Reuters.
- Marvell (MRVL) will showcase 2nm optical interconnect demonstrations aimed at next-generation AI data center connectivity at ECOC 2026.
Reviewing overnight developments:
Nikkei reported that Asia-Pacific markets were mostly higher amid lower oil prices and bond yields, while Japan was closed for Respect for the Aged Day.
In news:
- Nikkei reported that Treasury Secretary Bessent described his meeting with China’s foreign minister, He Lifeng, as successful, with discussions including trade negotiations and proposals for handling AI incidents.
- Japan’s markets will remain closed through September 23 for holidays.
In economic data:
- South Korea September exports 1-20 days 78.3% yr/yr (prior 56.0%) and imports 26.7% yr/yr (prior 19.0%) — Equity Markets —
- Japan’s Nikkei: closed for holiday
- Hong Kong’s Hang Seng: +1.2%
- China’s Shanghai Composite: +1.0%
- India’s Sensex: +0.8%
- South Korea’s Kospi: +1.7%
- Australia’s All Ordinaries: flat — FX — USD/JPY: +0.2% to 157.18 USD/INR: -0.2% to 95.865 USD/CNH: flat at 6.6938
European markets have opened with a positive bias in London and Frankfurt.
Mortgage Rates
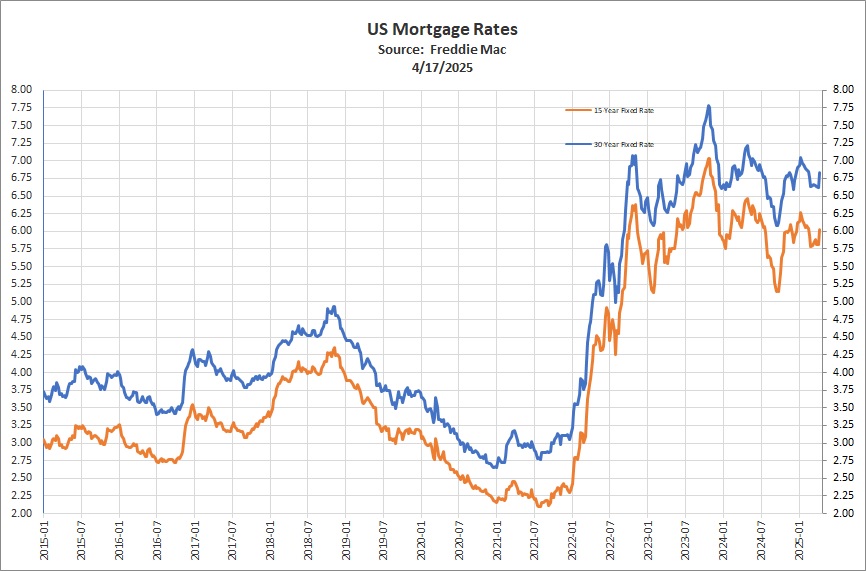
“The 30-year fixed-rate mortgage continues to fluctuate as markets assess economic data,” said Sam Khater, Freddie Mac’s Chief Economist.
The 30-year FRM averaged 6.95% as of September 17, 2026, up from last week when it averaged 6.76%. A year ago at this time, the 30-year FRM averaged 6.26%.
The 15-year FRM averaged 6.26%, up from last week when it averaged 6.09%. A year ago at this time, the 15-year FRM averaged 5.41%.
Freddie Mac’s Primary Mortgage Market Survey® is focused on conventional, conforming, fully amortizing home purchase loans for borrowers who put 20% down and have excellent credit. Average commitment rates should be reported along with average fees and points to reflect the total upfront cost of obtaining the mortgage. Borrowers may still pay closing costs which are not included in the survey.
Through our relationship with Mortgage Window, Inc. (NMLS 2485156) in Vancouver Washington we originate residential and reverse mortgages.
If you know someone age 62 or over who is feeling stressed financially and considering a reverse mortgage please send them this excellent piece with general information about reverse mortgages at: https://beaconrwa.com/reversemortgageguidebrwa/
Selected Cryptocurrencies
| Symbol | Name | Price | 24h % | 7d % | Market Cap | Volume(24h) |
| BTC | Bitcoin | $85,165.11 | 5.89% | 9.37% | $1.71T | $38.82B |
| ETH | Ethereum | $2,726.27 | 5.74% | 8.51% | $332.79B | $19.67B |
| BNB | BNB | $790.35 | 4.92% | 9.45% | $105.24B | $2.18B |
| XRP | XRP | $1.48 | 7.82% | 6.44% | $93.52B | $4.51B |
| SOL | Solana | $116.72 | 7.52% | 15.11% | $68.57B | $4.98B |
| TRX | TRON | $0.34 | 0.45% | 1.14% | $32.66B | $458.7M |
| ZEC | Zcash | $1,550.09 | 6.53% | 36.87% | $26.16B | $1.54B |
| HYPE | Hyperliquid | $95.53 | 4.49% | 19.05% | $24.11B | $1.04B |
| DOGE | Dogecoin | $0.09 | 9.80% | 11.13% | $14.57B | $1.63B |
| XMR | Monero | $572.09 | 8.82% | 11.60% | $10.75B | $213.13M |
| LINK | Chainlink | $13.06 | 7.96% | 14.68% | $9.77B | $547.86M |
| ADA | Cardano | $0.24 | 9.42% | 15.69% | $8.93B | $738.28M |
| LEO | UNUS SED LEO | $8.92 | -0.20% | -0.44% | $8.21B | $61.74K |
| XLM | Stellar | $0.21 | 10.91% | 11.08% | $7.36B | $341.69M |
| UNI | Uniswap | $8.87 | 1.60% | 40.91% | $5.51B | $1.09B |
| NEAR | NEAR Protocol | $4.20 | 16.34% | 73.94% | $5.49B | $2.28B |
| BCH | Bitcoin Cash | $266.65 | 8.10% | 19.38% | $5.39B | $279.09M |
| AVAX | Avalanche | $11.33 | 9.82% | 51.69% | $5.02B | $1.46B |
Data as of 5:15 AM PDT, Monday, September 21, 2026. Source: https://coinmarketcap.com
Sources: Bill Roller, BR Capital, Inc. dba Beacon Rock Wealth Advisors American Association for Individual Investors (AAII), Associated Press, Barclays Capital, Bloomberg, Briefing.com, Citigroup, Deutsche Bank, FactSet, Financial Times, Goldman Sachs, JPMorgan Asset Management, MarketfieldAsset Management, Morgan Stanley, MSCI, Morningstar, Northern Trust, Oppenheimer Funds, PIMCO, Standard & Poor’s, StockCharts.com, The Conference Board, Thomson Reuters, T. Rowe Price, U.S. Bureau of Economic Analysis, U.S. Federal Reserve, Wall Street Journal, The Washington Post. Index performance is shown as total return, which includes dividends, with the exception of MSCI-EM, which is quoted as price return/excluding dividends. Performance for the MSCI-EAFE and MSCI-EM indexes is quoted in U.S. Dollar investor terms.
The information above has been obtained from sources considered reliable, but no representation is made as to its completeness, accuracy or timeliness. All information and opinions expressed are subject to change without notice. Information provided in this report is not intended to be, and should not be construed as, investment, legal or tax advice; and does not constitute an offer, or a solicitation of any offer, to buy or sell any security, investment or other product BR Capital, Inc. dba Beacon Rock Wealth Advisors is a registered investment advisor.