Your Weekly Update for Tuesday, September 8, 2026.
Beacon Rock Wealth Advisors is a dba of BR Capital, Inc. It is a financial planning and registered investment advisory firm in Camas, Washington. We are always available to answer your questions. Give us a call at (360) 735-1900 or send an email.
If you or someone you know is worried about retirement, send us an email or give us a call for a no-obligation Retirement and Social Security Analysis.
If this information is helpful to you, please forward this to a friend and ask them to subscribe at https://newsletters.beaconrwa.com/subscribe.
Have a great week!
Bill Roller
NMLS #107972
CHARTERED FINANCIAL ANALYST
CERTIFIED FINANCIAL PLANNERTM
CHARTERED MARKET TECHNICIAN
bill.roller@beaconrwa.com
Summary
Markets were SLIGHTLY MIXED last week. The Dow Jones Industrial Average was DOWN 0.27% to 53,414.25 while the S&P500 ended UP 0.09% to 7,718.60. The Nasdaq Composite ROSE 0.40% to 26,506.99. The annual yield on the 30-year Treasury ROSE 4.0 basis point(s) to 5.246%.
Last Week
Closing Market Summary: Mixed finish caps volatile week for stocks
The major averages finished modestly lower on Friday as a stronger-than-expected August Employment Report increased expectations for a September rate hike, interrupting some of the positive momentum from Thursday’s broad advance. The S&P 500 (-0.4%), Nasdaq Composite (-0.3%), and DJIA (-0.5%) ended in negative territory, while the Russell 2000 (+0.3%) and S&P Mid Cap 400 (+0.1%) bucked the broader weakness with modest gains.
The employment report showed stronger-than-expected payroll growth and a lower-than-expected unemployment rate, prompting a meaningful shift in expectations for the Fed’s next policy move. The CME FedWatch Tool assigned roughly a 60% probability to a rate hike at the September FOMC meeting, up from about 50% yesterday. Cleveland Fed President Beth Hammack (voting FOMC member) added to the more hawkish policy backdrop, saying inflation remains too high, the labor market is stable, and current policy is not restrictive before concluding that “it’s time to act.”
Mega-cap stocks were mostly lower today, with the Vanguard Mega Cap Growth ETF finishing 0.5% lower. The consumer discretionary sector (-1.3%) was among the weakest performers as Tesla (TSLA 354.08, -22.28, -5.92%) gave back yesterday’s rally and lululemon athletica (LULU 100.61, -21.16, -17.38%) plunged following its earnings report.
The communication services sector (-0.9%) also struggled amid weakness across some of its largest components, while the financials sector (-0.8%) was another notable laggard.
The information technology sector (+0.2%) managed to finish higher despite a pronounced split beneath the surface. Semiconductor stocks rallied sharply, lifting the PHLX Semiconductor Index 3.4%, while software stocks moved firmly in the opposite direction and left the iShares GS Software ETF down 2.2%. Adobe (ADBE 266.51, -19.24, -6.73%) was among the software laggards after naming a new CEO.
Memory stocks were particularly strong within the semiconductor group. Sandisk (SNDK 1740.00, +185.01, +11.90%) surged more than 10% to finish as one of the day’s top gainers amid stronger DRAM and NAND pricing, robust server demand, broader strength across semiconductors, and a technical rebound from key moving averages.
Strength across semiconductor-related names also provided a boost to the industrials sector (+0.4%), which finished among the day’s better-performing areas.
Separately, credit bureau and credit-scoring stocks were a notable pocket of weakness following comments from FHFA Director Bill Pulte regarding potential changes to the mortgage credit-scoring market. FICO tumbled after Mr. Pulte said Fannie Mae and Freddie Mac will allow all lenders to use VantageScore, increasing competition for Fair Isaac’s (FICO 932.26, -186.67, -16.68%) mortgage-scoring business. Equifax (EFX 177.05, -12.04, -6.37%) and TransUnion (TRU 79.88, -5.04, -5.94%) also fell sharply after Mr. Pulte criticized credit reporting agencies over pricing and said he is considering a “bi-merge” system that would require mortgage lenders to pull two credit reports instead of three.
Meanwhile, WTI crude settled $0.15 higher (+0.2%) at $91.50 per barrel amid a relative lack of new developments surrounding the U.S.-Iran conflict. Crude gained roughly 10% for the week, with its sharp rise contributing to the equity market’s weakness during the first half of the week.
Friday’s modest decline ultimately left the major averages with a mixed finish to the week after a volatile stretch shaped by rising oil prices, elevated Treasury yields, and shifting expectations for monetary policy. Attention will remain firmly on the rate outlook next week, with the August Producer Price Index and Consumer Price Index providing the next major opportunities for expectations surrounding the September FOMC meeting to shift. The abbreviated week will be relatively light on the earnings front, although Oracle (ORCL 158.83, +4.79, +3.11%) reports after Thursday’s close.
U.S. Treasuries finished the week on a lower note after a strong jobs report for August prompted a reversal from a modestly higher start. The 2-year note yield settled up five basis points to 4.38% (+3 basis points this week), and the 10-year note yield settled up two basis points to 4.78% (+6 basis points this week).
- Russell 2000: +19.9% YTD
- S&P Mid Cap 400: +14.5% YTD
- Nasdaq Composite: +14.1% YTD
- S&P 500: +12.8% YTD
- DJIA: +11.1% YTD
Reviewing Friday’s data: August Nonfarm Payrolls 162K (Briefing.com consensus 45K); Prior was revised to 21K from -23K, August Nonfarm Private Payrolls 127K (Briefing.com consensus 45K); Prior was revised to 71K from 30K, August Unemployment Rate 4.1% (Briefing.com consensus 4.2%); Prior 4.1%, August Average Hourly Earnings 0.3% (Briefing.com consensus 0.2%); Prior was revised to 0.2% from 0.1%, August Average Workweek 34.4 (Briefing.com consensus 34.3); Prior 34.3 The quick takeaway by the market is that this report just might persuade the Fed to raise rates at its September FOMC meeting. The key takeaway, though, is that a rate hike in September is not assured by this August data. To that end, the 3-month average for total nonfarm payrolls was still just a modest 71,000, there was a moderation in average hourly earnings growth to 3.1% from 3.2% on a year-over-year basis, and persons unemployed for 27 weeks or more accounted for 27.0% of the unemployed versus 25.5% in July.
This Week
S&P futures vs fair value: -27.00. Nasdaq futures vs fair value: -23.00.
Equity futures point to a lower opening this morning as crude oil prices climb following an exchange of strikes between the U.S. and Iran over the weekend. The modest pressure comes after the major averages finished slightly higher last week despite considerable volatility surrounding oil prices, Treasury yields, and monetary policy expectations.
Attention this week will turn to the August Producer Price Index on Thursday and Consumer Price Index on Friday, both of which have the potential to shift expectations ahead of next week’s FOMC meeting. The market currently assigns roughly a 60% probability to a 25-basis point rate hike, according to the CME FedWatch tool.
On the U.S. data front: August NFIB Small Business Optimism 98.7 vs. 99.3 Briefing.com consensus; prior 99.8
Today’s remaining economic calendar: 3:00 PM ET: July Consumer Credit; Briefing.com consensus $11.3B; prior $14.2B
In corporate news:
- Anthropic is set to begin IPO marketing in October, according to Bloomberg.
- Intel (INTC 25, +4.45, +4.7%) trades higher amid reports of potential price increases.
- Roivant (ROIV38, +6.45, +18.47%) said the Phase 2 PHocus study of mosliciguat in PH-ILD met its primary and secondary endpoints, while the Phase 3 PHrontier study is underway.
Reviewing overnight developments:
Regional markets digested trade data from China and revised second-quarter growth figures from Japan. Japan’s Nikkei: -1.7%, Hong Kong’s Hang Seng: -0.4%, China’s Shanghai Composite: +0.2%, India’s Sensex: -0.7%, South Korea’s Kospi: -0.6%, Australia’s ASX All Ordinaries: -0.9%.
In news:
- South Korea is planning to build a gas power plant and eight nuclear power plants in the U.S. as part of a $200 billion investment project.
- China will release its August CPI and PPI readings overnight.
In economic data:
- China’s August trade surplus CNY809.30 bln (expected CNY805.00 bln; last CNY767.07 bln). August Imports 28.2% yr/yr (expected 30.0%; last 27.5%) and Exports 25.0% yr/yr, as expected (last 23.9%).
- Japan’s Q2 GDP 0.4% qtr/qtr (expected 0.3%; last 0.5%), Q2 GDP Capital Expenditure -0.9% qtr/qtr (expected -1.2%; last -0.7%), Q2 GDP Private Consumption 0.0% qtr/qtr, as expected (last 0.3%), and Q2 External Demand 0.5% qtr/qtr, as expected (last 0.3%). July Overall Wage Income 4.7% yr/yr (expected 3.9%; last 4.0%), July Overtime Pay 3.1% yr/yr (expected 3.9%; last 3.4%). July Current Account surplus JPY2.52 trln (expected JPY2.46 trln; last JPY1.40 trln). August Economy Watchers Current Index 46.4 (expected 46.3; last 45.7)
- South Korea’s Q2 GDP 0.6% qtr/qtr, as expected (last 1.7%); 3.7% yr/yr, as expected (last 3.6%)
- Australia’s September Westpac Consumer Sentiment -5.2% (last 6.0%). July Building Approvals -3.6% m/m, as expected (last 7.2%) and Private House Approvals -4.2% m/m (expected -4.2%; last 0.8%)
- New Zealand’s Q2 Manufacturing Sales Volume 0.8% qtr/qtr (last 3.6%)
Attention is on Thursday’s ECB decision along with political and fiscal developments in Germany and the UK. STOXX Europe 600: -0.1%, Germany’s DAX: -0.1%, U.K.’s FTSE 100: -0.1%, France’s CAC 40: UNCH, Italy’s FTSE MIB: -0.4%, Spain’s IBEX 35: -0.3%.
In news:
- The ECB is widely expected to announce a rate hike Thursday, with the statement likely to shape expectations for another possible increase in December.
- There is speculation that the British chancellor could announce tax increases in the Autumn budget address.
- Germany’s AfD won a weekend election in Saxony-Anhalt, doubling its support.
In economic data:
- Germany’s July trade surplus EUR21.3 bln (expected surplus of EUR16.0 bln; last surplus of EUR15.4 bln). July Imports -5.7% m/m (last 4.5%) and Exports -0.8% m/m (expected 0.0%; last 0.9%)
- France’s July trade deficit EUR6.7 bln (expected deficit of EUR6.0 bln; last deficit of EUR5.8 bln) and July Current Account deficit EUR4.7 bln (last deficit of EUR1.6 bln)
Mortgage Rates
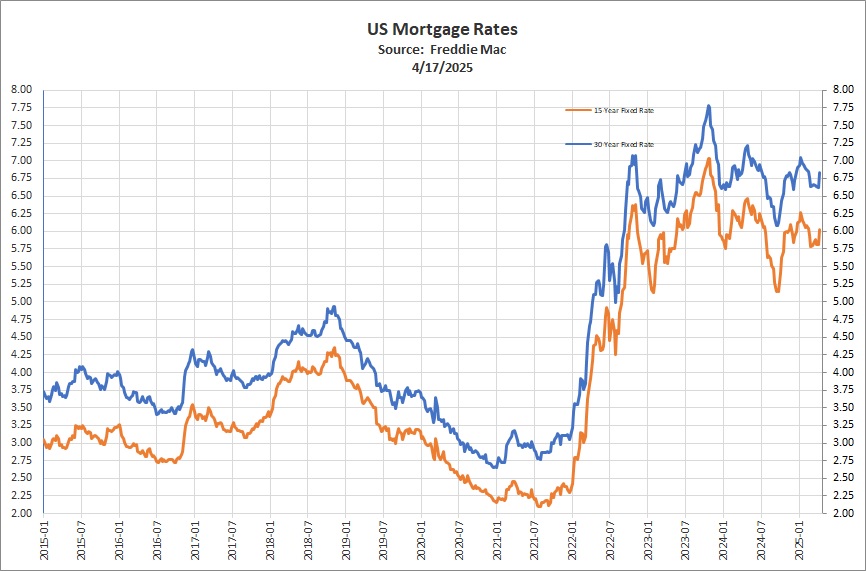
“The 30-year fixed-rate mortgage averaged 6.71% this week,” said Sam Khater, Freddie Mac’s Chief Economist. “Purchase demand has remained relatively stable indicating steady interest from buyers adapting to evolving market conditions.”
The 30-year FRM averaged 6.71% as of September 3, 2026, up from last week when it averaged 6.66%. A year ago at this time, the 30-year FRM averaged 6.50%.
The 15-year FRM averaged 6.04%, up from last week when it averaged 5.98%. A year ago at this time, the 15-year FRM averaged 5.60%.
Freddie Mac’s Primary Mortgage Market Survey® is focused on conventional, conforming, fully amortizing home purchase loans for borrowers who put 20% down and have excellent credit. Average commitment rates should be reported along with average fees and points to reflect the total upfront cost of obtaining the mortgage. Borrowers may still pay closing costs which are not included in the survey.
Through our relationship with Mortgage Window, Inc. (NMLS 2485156) in Vancouver Washington we originate residential and reverse mortgages.
If you know someone age 62 or over who is feeling stressed financially and considering a reverse mortgage please send them this excellent piece with general information about reverse mortgages at: https://beaconrwa.com/reversemortgageguidebrwa/
Selected Cryptocurrencies
| Symbol | Name | Price | 24h % | 7d % | Market Cap | Volume(24h) |
| BTC | Bitcoin | $78,383.39 | -1.26% | 0.29% | $1.57T | $29.59B |
| ETH | Ethereum | $2,472.40 | -0.66% | 0.41% | $301.7B | $12.18B |
| BNB | BNB | $752.13 | 1.06% | 9.41% | $100.15B | $1.78B |
| XRP | XRP | $1.39 | -0.41% | 0.59% | $87.38B | $2.08B |
| SOL | Solana | $102.76 | -1.99% | 0.35% | $60.23B | $2.73B |
| TRX | TRON | $0.34 | 0.61% | 2.90% | $32.13B | $428.68M |
| HYPE | Hyperliquid | $83.37 | -5.05% | -0.58% | $21B | $1.11B |
| ZEC | Zcash | $1,156.11 | -3.18% | 34.45% | $19.49B | $1.07B |
| DOGE | Dogecoin | $0.09 | -0.30% | 7.53% | $15.34B | $984.35M |
| XMR | Monero | $507.00 | -5.37% | -3.40% | $9.53B | $110.84M |
| LINK | Chainlink | $12.50 | -5.05% | 8.99% | $9.35B | $426.49M |
| LEO | UNUS SED LEO | $9.18 | 0.50% | -2.59% | $8.45B | $282.25K |
| ADA | Cardano | $0.22 | -0.97% | 8.59% | $7.98B | $471.82M |
| XLM | Stellar | $0.19 | -1.24% | 5.61% | $6.56B | $218.7M |
| BCH | Bitcoin Cash | $255.58 | -0.17% | 2.55% | $5.13B | $220.72M |
| UNI | Uniswap | $6.98 | -0.85% | 19.33% | $4.34B | $452.53M |
Data as of 5:00 AM PDT, Tuesday, September 8, 2026. Source: https://coinmarketcap.com
Sources: Bill Roller, BR Capital, Inc. dba Beacon Rock Wealth Advisors American Association for Individual Investors (AAII), Associated Press, Barclays Capital, Bloomberg, Briefing.com, Citigroup, Deutsche Bank, FactSet, Financial Times, Goldman Sachs, JPMorgan Asset Management, MarketfieldAsset Management, Morgan Stanley, MSCI, Morningstar, Northern Trust, Oppenheimer Funds, PIMCO, Standard & Poor’s, StockCharts.com, The Conference Board, Thomson Reuters, T. Rowe Price, U.S. Bureau of Economic Analysis, U.S. Federal Reserve, Wall Street Journal, The Washington Post. Index performance is shown as total return, which includes dividends, with the exception of MSCI-EM, which is quoted as price return/excluding dividends. Performance for the MSCI-EAFE and MSCI-EM indexes is quoted in U.S. Dollar investor terms.
The information above has been obtained from sources considered reliable, but no representation is made as to its completeness, accuracy or timeliness. All information and opinions expressed are subject to change without notice. Information provided in this report is not intended to be, and should not be construed as, investment, legal or tax advice; and does not constitute an offer, or a solicitation of any offer, to buy or sell any security, investment or other product BR Capital, Inc. dba Beacon Rock Wealth Advisors is a registered investment advisor.