Your Weekly Update for Monday, August 17, 2026.
Beacon Rock Wealth Advisors is a dba of BR Capital, Inc. It is a financial planning and registered investment advisory firm in Camas, Washington. We are always available to answer your questions. Give us a call at (360) 735-1900 or send an email.
If you or someone you know is worried about retirement, send us an email or give us a call for a no-obligation Retirement and Social Security Analysis.
If this information is helpful to you, please forward this to a friend and ask them to subscribe at https://newsletters.beaconrwa.com/subscribe.
Have a great week!
Bill Roller
NMLS #107972
CHARTERED FINANCIAL ANALYST
CERTIFIED FINANCIAL PLANNERTM
CHARTERED MARKET TECHNICIAN
bill.roller@beaconrwa.com
Summary
Markets were FLATLY MIXED last week. The Dow Jones Industrial Average was DOWN 0.56% to 53,732.41 while the S&P500 ended UP 0.36% to 7,785.76. The Nasdaq Composite ROSE 0.14% to 26,729.16. The annual yield on the 30-year Treasury ROSE 5.4 basis point(s) to 5.265%.
Last Week
Closing Market Summary: Stocks consolidate after record-setting advance
Stocks ended a relatively quiet Friday session with modest losses, pulling back from yesterday’s record-setting advance as weakness in mega-cap technology stocks and a midday rise in Treasury yields weighed on the major averages. The S&P 500 (-0.2%), Nasdaq Composite (-0.3%), and DJIA (-0.2%) finished lower, though the S&P 500 and Nasdaq Composite still notched modest gains for the week.
The major averages opened slightly higher before gradually slipping into negative territory as the morning progressed. The move coincided with a rise in longer-dated Treasury yields, with the 10-year note yield climbing six basis points to 4.70% despite a weaker-than-expected July retail sales report. The increase in yields provided a modest headwind following a week in which largely favorable CPI and PPI readings had eased concerns about additional Fed tightening.
Most of the pressure at the index level came from growth stocks. The Vanguard Mega Cap Growth ETF fell 0.5%, while the information technology sector (-0.4%) was among the laggards as some of yesterday’s strongest areas gave back ground. The PHLX Semiconductor Index slipped 0.3%, with Applied Materials (AMAT 507.18, -27.36, -5.12%) facing some profit-taking following a solid earnings report and Broadcom (AVGO 392.99, -24.83, -5.94%) also among the large-cap chip laggards. Continued strength in memory stocks helped offset some of that weakness, as Sandisk (SNDK 1641.11, +113.00, +7.39%) extended its rally following yesterday’s investor day after JPMorgan resumed coverage with an Overweight rating and a $2,250 price target.
Software stocks saw more pronounced profit-taking following yesterday afternoon’s rally, leaving the iShares GS Software ETF (IGV) down 2.1%. Workday (WDAY 198.68, -7.77, -3.76%) also gave back some of yesterday’s roughly 18% surge that followed reports that Silver Lake is in talks to acquire the company.
The consumer discretionary sector (-0.4%) also lagged amid weakness in mega-cap stocks and retail names ahead of a busy slate of earnings from the group next week.
Still, the broader market held up better than the major averages. Six S&P 500 sectors finished higher, and the S&P 500 Equal Weight Index ended flat, while the Russell 2000 (+0.5%) and S&P MidCap 400 (+0.3%) both advanced and reached fresh record highs during the session.
Energy (+1.4%) was the clear sector leader as crude oil resumed its climb despite little new geopolitical news. WTI crude settled $1.34 higher (+1.7%) at $82.40 per barrel, bringing its gain for the week to roughly 5%.
The utilities (+0.6%) and materials (+0.5%) sectors also outperformed, with higher precious metals prices supporting the latter.
Outside the current S&P 500 membership, Reddit (RDDT 177.97, +19.85, +12.55%) surged on news that the company will join the index next week.
Friday’s subdued pullback ultimately looked more like consolidation following Thursday’s record-setting advance than a meaningful shift in sentiment. The S&P 500 still finished the week higher after the July CPI and PPI reports helped ease concerns about additional Fed tightening, while the relative strength in the equal-weight index and smaller-cap stocks showed that Friday’s weakness was concentrated largely in some of the market’s biggest growth names.
U.S. Treasuries retreated on Friday, producing losses for the week in 10 and 30 year note yields while the front end also faced some pressure today, but the 2-year note still ended the week with a gain. The 2-year note yield settled up three basis points to 4.17% (-4 basis points this week), and the 10-year note yield settled up six basis points to 4.70% (+4 basis points this week).
- Russell 2000: +23.6% YTD
- S&P Mid Cap 400: +18.8% YTD
- Nasdaq Composite: +15.0% YTD
- S&P 500: +13.7% YTD
- DJIA: +11.8% YTD
Reviewing today’s data:
- July Retail Sales -0.6% (Briefing.com consensus 0.2%); Prior 0.2%, July Retail Sales, ex-auto -0.3% (Briefing.com consensus 0.2%); Prior -0.2%. The key takeaway from the report is that control retail sales dropped 0.4% month-over-month. This figure will feed into GDP forecasts, so there are apt to be some downward revisions to Q3 GDP forecasts.
- June Business Inventories 0.0% (Briefing.com consensus 0.1%); Prior was revised to 0.4% from 0.3%
- August Univ. of Michigan Consumer Sentiment – Prelim 51.0 (Briefing.com consensus 54.5); Prior 55.2. The key takeaway from the report is that only 8% of all consumers surveyed expect their income growth to exceed inflation in the year ahead. That expectation could ultimately translate into lower discretionary spending activity.
This Week
S&P futures vs fair value: +2.00. Nasdaq futures vs fair value: +134.00.
Equity futures point to a mostly higher open this morning as the stock market looks to kick off a week that could be relatively devoid of market-moving catalysts. The S&P 500 is set to open just above its baseline after a relatively quiet previous week, though the index did set new record highs and extended its weekly winning streak to three weeks.
A strong Q2 earnings season continues to wind down, though a host of notable retailer names are set to report results this week.
On the geopolitical front, oil is flat as the U.S.-Iran ceasefire is set to expire today. CNBC reports that tanker traffic through the Strait of Hormuz remains exceptionally low.
Stocks weathered higher oil prices last week, with some relief coming from easing expectations of Fed tightening after several tame inflation readings. There are only a few data points on the calendar this morning (none of which are typically market movers) to kick off a relatively quiet week of releases.
In corporate news:
- Alibaba (BABA 88, +3.07, +2.5%) is aiming to sell game developer unit Lingxi Games for more than $2 billion, according to Reuters.
- Memory names are trading higher in the premarket after U.S. Secretary of Commerce Howard Lutnick said that the Trump administration does not want Apple (AAPL 15, +1.22, +0.4%) buying Chinese memory chips, according to The Wall Street Journal.
- NVIDIA(NVDA 74, +1.58, +0.7%) downsized plans to guarantee a $250 billion OpenAI Ohio data center, according to The Wall Street Journal.
Reviewing overnight developments:
Equity indices in the Asia-Pacific region began the week on a mostly higher note while South Korea’s markets were closed for a holiday. Japan’s Nikkei: +0.7%, Hong Kong’s Hang Seng: +1.3%, China’s Shanghai Composite: +1.4%, India’s Sensex: -0.4%, South Korea’s Kospi: CLOSED, Australia’s ASX All Ordinaries: -0.4%.
In news:
- China’s growth figures for July were shy of expectations while Japan’s flash Q2 GDP report (0.3% qtr/qtr; 0.5% expected) was also underwhelming, hurt by high prices and lower business spending.
- JGBs retreated despite the miss since the market remains on watch for more rate hikes from the Bank of Japan.
- President Trump scaled back annual joint U.S.-South Korea military exercises.
- Alphabet is planning to sell Australia dollar-denominated debt.
In economic data:
- China’s July Industrial Production 4.5% yr/yr (expected 5.0%; last 5.3%), July Fixed Asset Investment -6.7% yr/yr (expected -6.2%; last -5.7%), July Retail Sales 0.6% yr/yr (expected 1.5%; last 1.0%), July Unemployment Rate 5.2% (expected 5.1%; last 5.0%)
- Japan’s flash Q2 GDP 0.3% qtr/qtr (expected 0.5%; last 0.5%); 1.1% yr/yr (expected 2.0%; last 1.9%). Q2 GDP Capital Expenditure -1.2% qtr/qtr (expected 0.4%; last -1.0%), Q2 GDP External Demand 0.5% qtr/qtr (expected 0.3%; last 0.3%). Q2 GDP Private Consumption 0.0% qtr/qtr (expected 0.5%; last 0.5%). Q2 GDP Price Index 2.6% yr/yr (expected 2.4%; last 3.2%). June Industrial Production 1.9% m/m (expected 1.3%; last 0.1%) and Capacity Utilization 4.1% m/m (last 0.1%)
- South Korea’s July trade surplus $30.39 bln (expected $30.32 bln; last $36.09 bln). July Imports 26.5% yr/yr, as expected (last 30.0%) and Exports 63.0% yr/yr (expected 62.8%; last 70.7%)
- Singapore’s July trade surplus SGD10.72 bln (last surplus of SGD13.87 bln). July non-oil Exports -0.3% m/m (last -8.8%); 24.2% yr/yr (last 24.4%)
- New Zealand’s July Performance of Services Index 50.6 (last 50.9). July Electronic Card Retail Sales 1.3% m/m (last -1.3%); 3.4% yr/yr (last 1.3%). July FPI 0.1% m/m (last 0.6%)
Major European indices trade near their flat lines while Italy’s MIB (+0.4%) outperforms with help from STMicroelectronics, Ferrari, and select bank stocks. STOXX Europe 600: +0.1%, Germany’s DAX: +0.1%, U.K.’s FTSE 100: +0.2%, France’s CAC 40: -0.1%, Italy’s FTSE MIB: +0.4%, Spain’s IBEX 35: -0.2%.
In news:
- Swiss food distributor SIG Group is down more than 15% after announcing an unexpected CEO change.
- There is growing focus on the U.K.’s property market after Rightmove reported a sharp drop in average new listed asking prices for homes.
- Fitch affirmed the U.K.’s AA- rating with a Stable outlook.
There is no economic data of note today.
Mortgage Rates
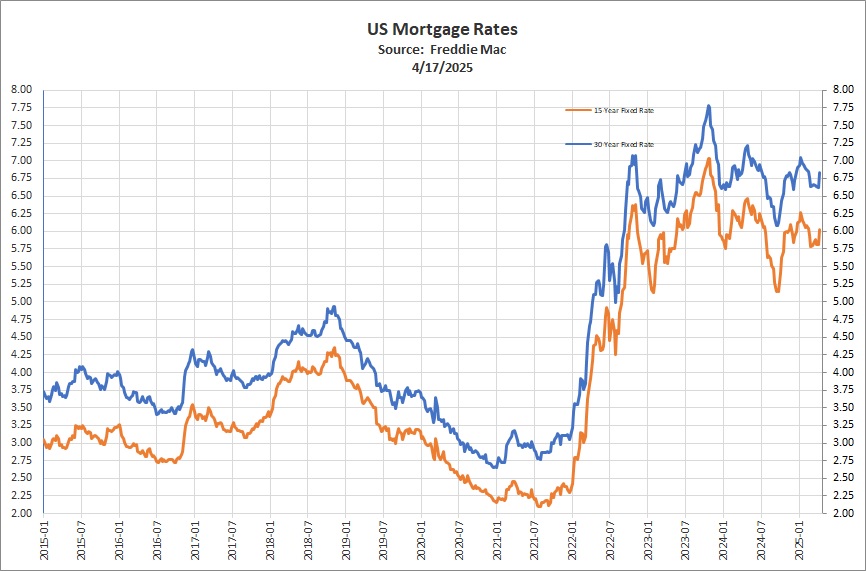
“Mortgage rates remained relatively stable this week at 6.67%,” said Sam Khater, Freddie Mac’s Chief Economist. “Housing affordability has improved from a year ago, and recent increases in purchase and refinance applications suggest that borrowers continue to respond to even modest changes in mortgage rates.”
The 30-year FRM averaged 6.67% as of August 13, 2026, down from last week when it averaged 6.69%. A year ago at this time, the 30-year FRM averaged 6.58%.
The 15-year FRM averaged 5.96%, down from last week when it averaged 6.01%. A year ago at this time, the 15-year FRM averaged 5.71%.
Selected Cryptocurrencies
| Symbol | Name | Price | 24h % | 7d % | Market Cap | Volume(24h) |
| BTC | Bitcoin | $63,554.55 | 0.96% | -2.22% | $1.27T | $14.73B |
| ETH | Ethereum | $1,898.17 | 1.05% | -0.89% | $229.07B | $6.36B |
| BNB | BNB | $603.82 | -0.44% | -0.02% | $80.4B | $1.02B |
| XRP | XRP | $1.00 | -0.10% | -3.23% | $62.6B | $813.13M |
| SOL | Solana | $75.34 | 0.21% | -1.97% | $43.92B | $1.2B |
| TRX | TRON | $0.33 | 0.15% | 0.18% | $31.49B | $336.32M |
| HYPE | Hyperliquid | $59.26 | 3.61% | 7.57% | $14.96B | $220.94M |
| DOGE | Dogecoin | $0.07 | 0.38% | 0.15% | $10.89B | $281.1M |
| LEO | UNUS SED LEO | $9.43 | 1.38% | -2.19% | $8.67B | $318.79K |
| ZEC | Zcash | $510.64 | 5.37% | 1.41% | $8.59B | $336.28M |
| XMR | Monero | $414.12 | 0.95% | 4.14% | $7.78B | $79.9M |
| LINK | Chainlink | $9.52 | 1.94% | 14.46% | $7.12B | $257.91M |
| ADA | Cardano | $0.17 | -1.48% | -11.35% | $6.36B | $208.81M |
| XLM | Stellar | $0.16 | 0.54% | -3.43% | $5.44B | $67.15M |
| BCH | Bitcoin Cash | $203.93 | 0.08% | -5.34% | $4.09B | $143.62M |
| USD1 | World Liberty Financial USD | $1.00 | 0.00% | -0.06% | $3.98B | $532.62M |
Data as of 5:30 AM PDT, Monday, August 17, 2026. Source: https://coinmarketcap.com
If you know someone age 62 or over who is feeling stressed financially and considering a reverse mortgage please send them this excellent piece with general information about reverse mortgages at: https://beaconrwa.com/reversemortgageguidebrwa/
Sources: Bill Roller, BR Capital, Inc. dba Beacon Rock Wealth Advisors American Association for Individual Investors (AAII), Associated Press, Barclays Capital, Bloomberg, Briefing.com, Citigroup, Deutsche Bank, FactSet, Financial Times, Goldman Sachs, JPMorgan Asset Management, MarketfieldAsset Management, Morgan Stanley, MSCI, Morningstar, Northern Trust, Oppenheimer Funds, PIMCO, Standard & Poor’s, StockCharts.com, The Conference Board, Thomson Reuters, T. Rowe Price, U.S. Bureau of Economic Analysis, U.S. Federal Reserve, Wall Street Journal, The Washington Post. Index performance is shown as total return, which includes dividends, with the exception of MSCI-EM, which is quoted as price return/excluding dividends. Performance for the MSCI-EAFE and MSCI-EM indexes is quoted in U.S. Dollar investor terms.
The information above has been obtained from sources considered reliable, but no representation is made as to its completeness, accuracy or timeliness. All information and opinions expressed are subject to change without notice. Information provided in this report is not intended to be, and should not be construed as, investment, legal or tax advice; and does not constitute an offer, or a solicitation of any offer, to buy or sell any security, investment or other product BR Capital, Inc. dba Beacon Rock Wealth Advisors is a registered investment advisor.